
Markets head into the week of September 21-25 in the immediate aftermath of the Federal Reserve’s first rate hike since 2023. With the big policy decision behind them, traders now shift focus to a lighter data calendar, a wall of Fed commentary, and Wednesday’s flash PMI readings.
Last week’s headline: the Fed hiked
On September 16, the FOMC voted 12-0 to raise the federal funds rate by 25 basis points to a target range of 3.75%-4.00%, its first increase since July 2023. The updated Summary of Economic Projections showed 16 of 18 policymakers expecting at least one more hike before year-end, with the median dot pointing to a year-end range of roughly 4.00%-4.25%. Fed Chair Kevin Warsh offered limited forward guidance at his press conference but emphasized that inflation remains too high. The next FOMC decision is October 28.
This week’s calendar
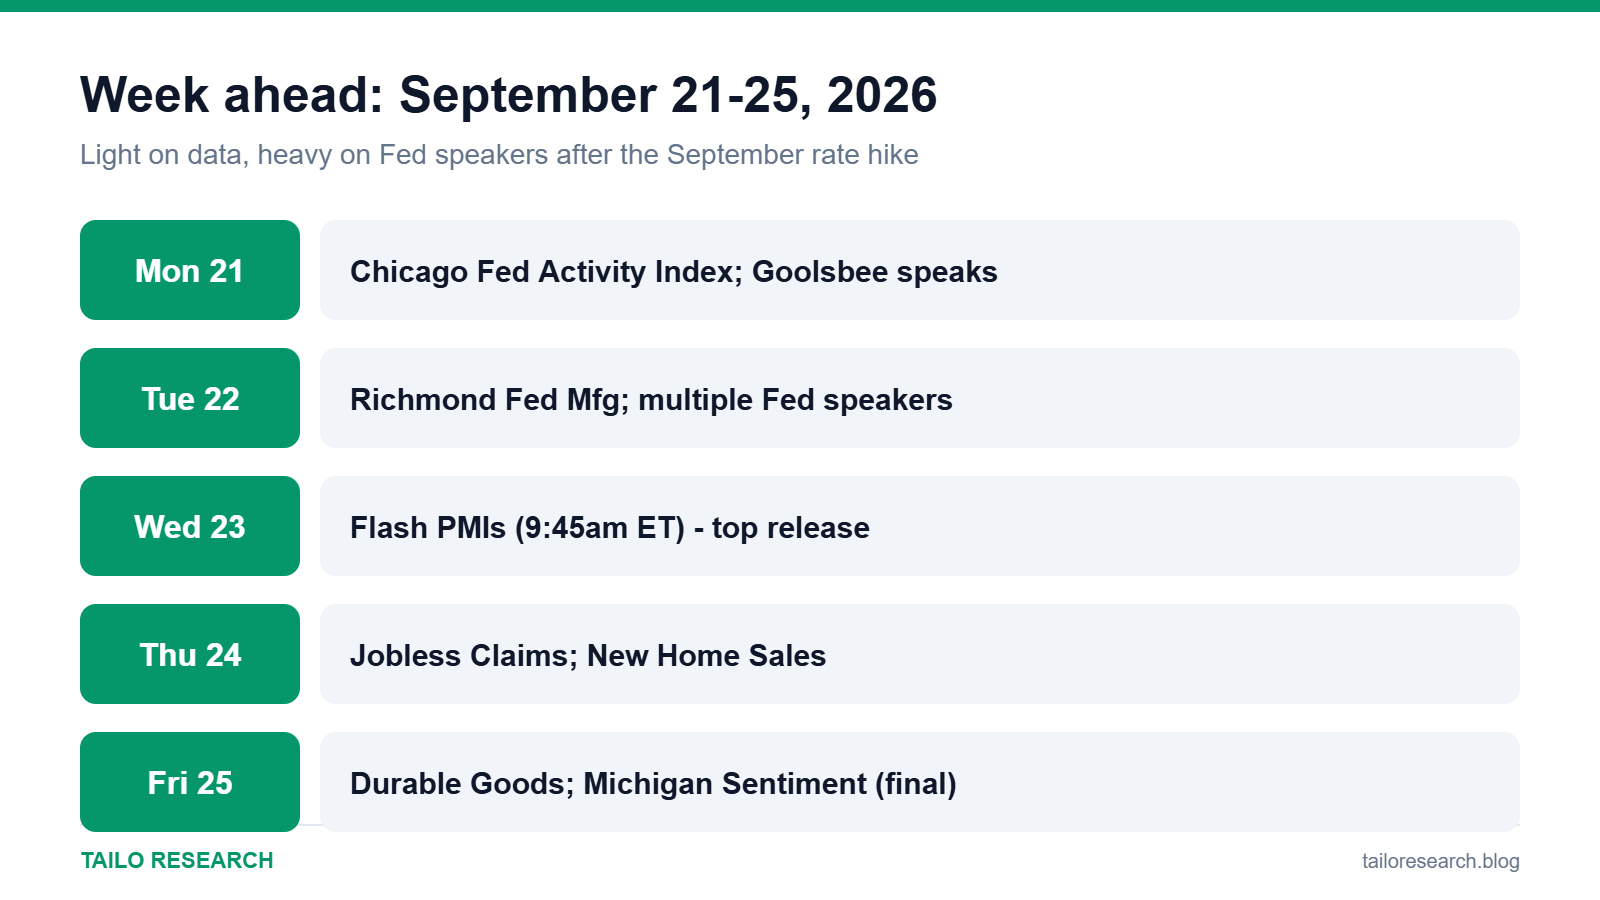
| Day | Event | Why it matters |
|---|---|---|
| Mon, Sep 21 | Chicago Fed National Activity Index; Fed’s Goolsbee speaks | First look at growth momentum after the hike |
| Tue, Sep 22 | Richmond Fed Manufacturing; multiple Fed speakers | More clues on the pace of further hikes |
| Wed, Sep 23 | S&P Global Flash Manufacturing & Services PMIs (9:45am ET) | The week’s top-tier release; a real-time growth signal |
| Thu, Sep 24 | Initial Jobless Claims; New Home Sales | Labor market and housing health checks |
| Fri, Sep 25 | Durable Goods Orders; final U. of Michigan Consumer Sentiment | Closes the week on consumer and capex signals |
Beyond the US docket, Fed officials Williams, Barkin, Hammack and Paulson are all scheduled to speak this week, alongside central bankers from the ECB, BoE, SNB and others. With no fewer than 10 Fed appearances on tap, tone matters as much as any single data point: markets will be listening for how officials frame the path to the next hike.
What traders are watching
- Whether Wednesday’s flash PMIs confirm the “solid pace” of growth the Fed described in its statement
- Any shift in Fed speakers’ tone toward or away from an October move
- How equity indices, including the Nasdaq-100 and S&P 500, digest a rate backdrop that is tightening rather than easing
- Dollar and Treasury yield direction, both of which repriced higher after the September decision
Why a hike, not a cut, changes the setup
For most of 2025 the conversation was about rate cuts. September’s hike flips that script: borrowing costs are rising again, and Fed projections point to at least one more increase in 2026. That has direct implications for leveraged instruments. Margin costs on positions such as futures and CFDs can be sensitive to the broader rate environment, and higher-for-longer policy tends to pressure the valuation multiples that growth and technology stocks trade on.
Key levels to watch this week
Rather than predicting a direction, the more useful habit going into a data-heavy week is knowing your levels ahead of time. Our guides to support and resistance and how to trade a level cover how to plan entries and stops before volatility hits, which matters most around PMI releases and Fed commentary.
Key takeaways
- The Fed raised rates to 3.75%-4.00% on September 16, its first hike since 2023, with more likely before year-end.
- This week’s data is light but Fed speak is heavy, with Wednesday’s flash PMIs the top release.
- The next FOMC decision is October 28; until then, tone from Fed speakers is the main catalyst.
Want to trade what you read here as a CFD alongside TradingView charts? Open a Vantage account. This is an affiliate link: we may earn a commission at no extra charge from us. CFDs are complex instruments and carry a high risk of losing money rapidly due to leverage; most retail accounts lose money. See our Affiliate Disclosure and Risk Disclaimer.
Educational content only, not investment advice. Trading and investing involve risk, including the loss of your capital. Read our Risk Disclaimer and Affiliate Disclosure.


Leave a Reply