
Vantage operates through five separately regulated legal entities, and the safety of your funds depends on which one holds your account. This guide breaks down what each regulator actually requires and how to check which entity applies to you.
Vantage’s regulatory entities
| Regulator | Region | Entity |
|---|---|---|
| FCA | United Kingdom | Vantage Global Prime LLP |
| ASIC | Australia | Vantage Global Prime Pty Ltd |
| FSCA | South Africa | Vantage Markets (Pty) Ltd |
| CIMA | Cayman Islands | Vantage International Group Limited |
| VFSC | Vanuatu | Vantage Global Limited |
What Tier-1 regulation actually requires
- Segregated client funds: client money held separately from Vantage’s own operating capital
- Capital adequacy requirements: the regulated entity must maintain minimum capital reserves
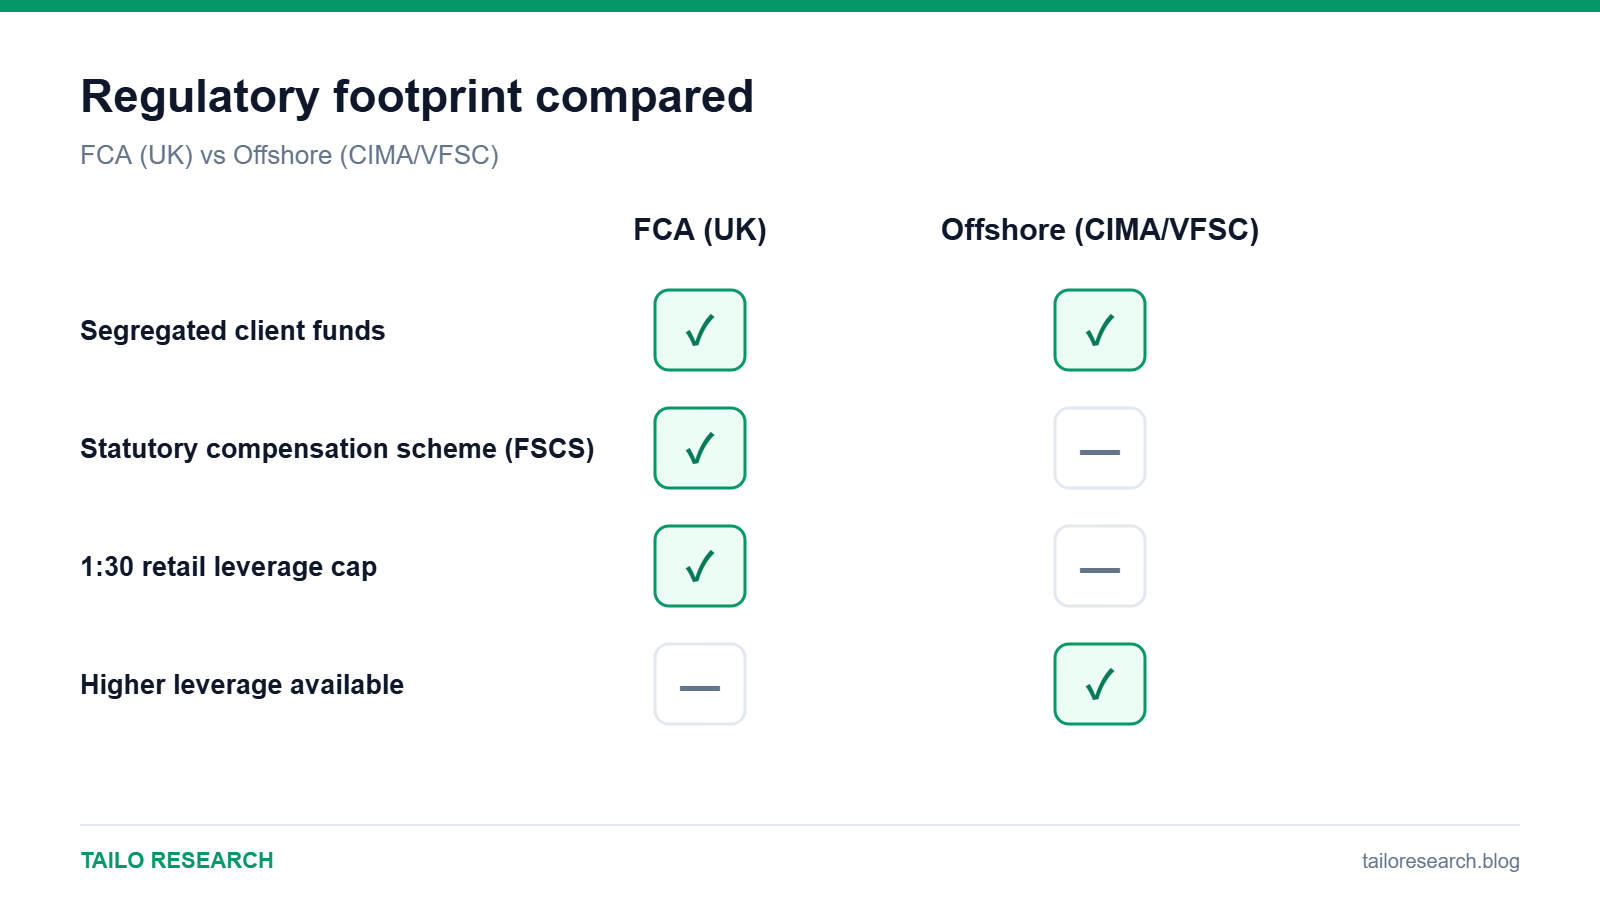
- Retail leverage caps: 1:30 on major pairs and indices under FCA and ASIC rules
- Regular audits and reporting: to the regulator on an ongoing basis
FCA clients: FSCS protection
Clients onboarded under Vantage’s FCA-regulated UK entity may be eligible for protection under the Financial Services Compensation Scheme (FSCS) if the firm becomes insolvent, up to the scheme’s published limits for investment claims. This is one of the stronger investor-protection frameworks available among CFD brokers and does not apply automatically to Vantage’s offshore entities.
Offshore entities: what changes
Clients onboarded under Vantage’s CIMA (Cayman Islands) or VFSC (Vanuatu) entities generally get segregated funds and regulatory oversight, but not a statutory compensation scheme equivalent to the FCA’s FSCS. In exchange, these entities typically offer significantly higher leverage than the 1:30 cap that applies under FCA and ASIC. Higher leverage increases risk rather than reducing it, so this is a trade-off, not a straightforward upgrade.
How to check which entity you are under
- Review your account opening documents or client agreement, which name the specific Vantage entity
- Cross-check that entity’s license number on the relevant regulator’s public register (FCA, ASIC, FSCA, CIMA or VFSC)
- If unclear, contact Vantage support directly and ask which entity your account was opened under
Other safety signals worth checking
- Negative balance protection, which prevents losing more than your deposited funds
- Whether client funds are held at recognized, regulated banking institutions
- How long the broker has operated without major regulatory sanctions
Key takeaways
- Vantage’s safety depends on which of its five regulated entities holds your account, not on the brand as a whole.
- FCA-regulated clients may qualify for FSCS protection; offshore entities generally do not offer an equivalent scheme.
- Always confirm your entity and its license number on the regulator’s own public register.
Ready to open an account? Open a Vantage account. This is an affiliate link: we may earn a commission at no extra charge from us. CFDs are complex instruments and carry a high risk of losing money rapidly due to leverage; most retail accounts lose money.
Educational content only, not investment advice. Trading and investing involve risk, including the loss of your capital. Read our Risk Disclaimer and Affiliate Disclosure.


Leave a Reply